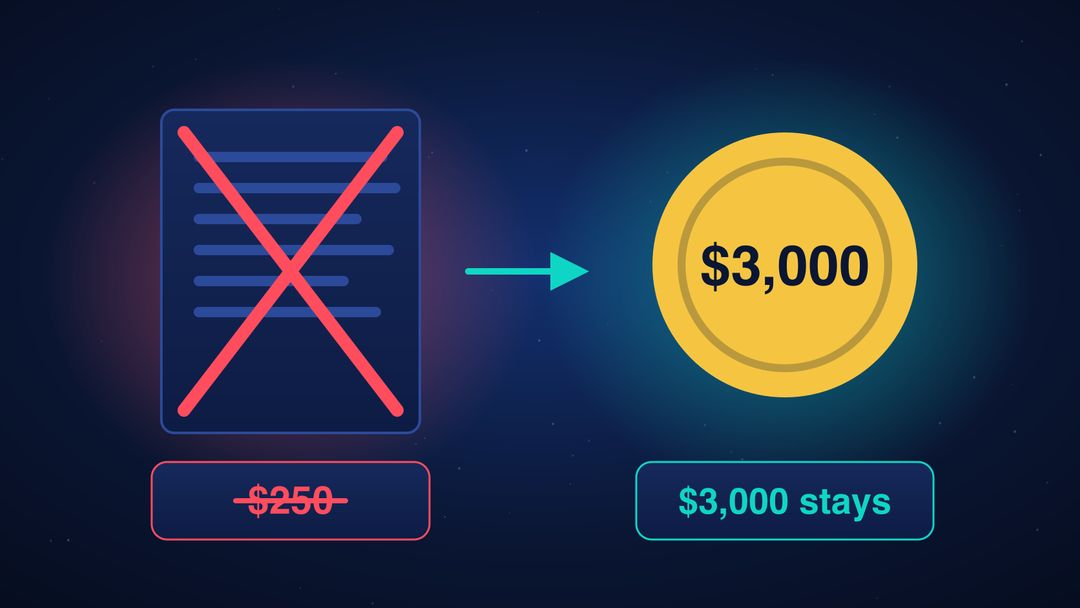
A plan that had hung over crypto transfers for six years is gone. On Friday, November 6, 2026, the Treasury’s financial crimes unit, FinCEN, and the Federal Reserve announced that they are withdrawing a 2020 proposal that would have sharply lowered the amount at which financial firms must record and pass on details of a transfer. The current $3,000 limit stays.
Key facts
- What was dropped: a joint proposal published on October 27, 2020.
- The lower limit: it would have cut the threshold from $3,000 to $250 for transfers that begin or end outside the United States.
- The crypto part: it would also have stated that these rules cover crypto, in both domestic and cross-border transfers, along with digital assets that have legal tender status.
- When it takes effect: on publication in the Federal Register, scheduled for Monday, November 9.
- What happens next: the agencies say they will take no further action on this proposal.
What the travel rule does
Two linked US rules are involved. The Recordkeeping Rule makes banks and other financial firms collect and keep information on transfers. The Travel Rule makes them send that information along to the next firm in the payment chain, so the details “travel” with the money.
Both apply to transfers of $3,000 or more. That figure dates from 1995.
The withdrawal does not free crypto from these rules. It removes a proposal to change them, and FinCEN’s existing guidance from 2019 already treats crypto transfers by money transmitters as covered.
Why the agencies pulled it
The notice gives two main reasons:
- Age. More than five years have passed, and the agencies want fresh public feedback before adopting anything similar.
- A changed industry. They say crypto markets have matured and new legal frameworks are emerging, pointing to the GENIUS Act, the US stablecoin law enacted on July 18, 2025.
The proposal drew nearly 3,000 comments, most of them form letters. Critics said a $250 limit would burden smaller institutions, disrupt remittances and create more stored personal data. Some called it an invasion of privacy. Some wanted the limit raised instead, because of inflation since 1995. Crypto companies mostly opposed the crypto section, while some banks and money services businesses supported it.
Not the end of the story
This is not a promise that the limit will never fall. The agencies say the withdrawal gives certainty that no final rule will come without another chance for public comment. They also talk about “future, potential amendments” for crypto, to be weighed against recent developments.
It is also the second such step in about a month. In October, FinCEN withdrew two other crypto proposals, one on reports, records and identity checks for certain transactions and one on crypto mixing.
None of this signals a retreat from enforcement. On the same day, FinCEN issued its order cutting crypto exchange MEXC off from the US financial system.
Why it matters
A $250 limit would have reached far more everyday cross-border transfers, including small remittances, and pushed firms to collect and store much more personal data. Dropping it spares financial firms that work and leaves the line where it has been for three decades.
For crypto, the bigger point is that the question stays open. Washington is not abandoning oversight of transfers, but any new version would be written for today’s market, after a new round of public comment.
This article is for information only and is not financial advice.